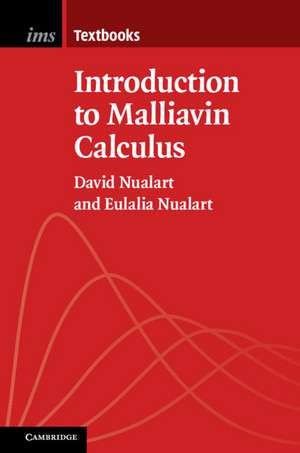
Introduction to Malliavin Calculus
Autor David Nualart, Eulalia Nualarten Limba Engleză Paperback – 30 noi 2018
Preț: 353.57 lei
Puncte Express: 530
Carte tipărită la comandă
Livrare economică 08-22 decembrie
Livrare prin curier în România Termenul estimat este afișat lângă disponibilitate.
Transport gratuit de la 400.00 lei Plată online sau ramburs, în funcție de opțiunile comenzii.
Retur gratuit în 14 zile Comandă securizată și suport în română.
Specificații
ISBN-13: 9781107611986
ISBN-10: 1107611989
Pagini: 250
Dimensiuni: 152 x 229 x 14 mm
Greutate: 0.35 kg
Editura: Cambridge University Press
Locul publicării:New York, United States
ISBN-10: 1107611989
Pagini: 250
Dimensiuni: 152 x 229 x 14 mm
Greutate: 0.35 kg
Editura: Cambridge University Press
Locul publicării:New York, United States
V-ar putea interesa
-
 Non-Standard Parametric Statistical InferenceRussell Cheng-25%Preț: 895.40 lei1196.65 lei
-
 Teaching Statistics: A Bag of TricksAndrew Gelman-20%Preț: 301.98 lei375.19 lei
-
 Martingales and Stochastic IntegralsP. E. KoppPreț: 431.15 lei
-
 An Analytical CalculusEdwin A. MaxwellPreț: 338.35 lei
-
 Topics in Applied Multivariate AnalysisD. M. HawkinsPreț: 369.76 lei
-
 Probabilistic Properties of Deterministic SystemsAndrzej LasotaPreț: 460.54 lei
-
 Measurement TheoryFred S. Roberts-11%Preț: 572.60 lei643.38 lei
-
 Empirical Processes in M-EstimationSara A. van de GeerPreț: 449.14 lei
-
 Stopping Times and Directed ProcessesG. A. EdgarPreț: 474.30 lei
-
 Higher MechanicsHorace LambPreț: 331.80 lei
-
 Statistics (The Easier Way) With RNicole M. RadziwillPreț: 350.58 lei
-
 Bayesian Models for Astrophysical DataJoseph M. Hilbe-11%Preț: 602.41 lei676.87 lei
-
 An Elementary Course of Infinitesimal CalculusHorace Lamb-19%Preț: 437.63 lei540.28 lei
-
 Malliavin Calculus and Stochastic AnalysisFrederi Viens-15%Preț: 686.04 lei807.10 lei
-
 Multi-Period Trading via Convex OptimizationStephen BoydPreț: 379.93 lei
-
 Introductory StatisticsBarbara IllowskyPreț: 314.00 lei
-
 Lectures on Probability Theory and StatisticsMartin T. BarlowPreț: 388.24 lei
-
 Preț: 320.67 lei
-
 The Malliavin Calculus and Related TopicsDavid Nualart-15%Preț: 705.76 lei830.30 lei
-
 Malliavin Calculus at Saint-FlourNobuyuki IkedaPreț: 361.15 lei
-
 Stochastic Inequalities and ApplicationsEvariste Giné-15%Preț: 627.93 lei738.74 lei
-
 Stochastic DynamicsSoren R K NielsenPreț: 178.50 lei
-
 RISK THEORYKonstantinides Dimitrios G-18%Preț: 1075.51 lei1311.60 lei
-
 STOCH ANAL, STOCH SYST, & APPL TO FINANTsoi Allanus-15%Preț: 599.01 lei704.72 lei
Cuprins
Preface; 1. Brownian motion; 2. Stochastic calculus; 3. Derivative and divergence operators; 4. Wiener chaos; 5. Ornstein-Uhlenbeck semigroup; 6. Stochastic integral representations; 7. Study of densities; 8. Normal approximations; 9. Jump processes; 10. Malliavin calculus for jump processes I; 11. Malliavin calculus for jump processes II; Appendix A. Basics of stochastic processes; References; Index.
Recenzii
'This book is a delightful and self-contained introduction to stochastic and Malliavin calculus that will guide the graduate students in probability theory from the basics of the theory to the borders of contemporary research. It is a must read written by two globally recognized experts!' Fabrice Baudoin, University of Connecticut
'Malliavin calculus has seen a great revival of interest in recent years, after the discovery about ten years ago that Stein's method for probabilistic approximation and Malliavin calculus fit together admirably well. Such an interaction has led to some remarkable limit theorems for Gaussian, Poisson and Rademacher functionals. This monograph, written by two internationally renowned specialists of the field, provides a concise, self-contained and very pleasant exposition of different aspects of this rich and recent line of research. For sure, it is destined to quickly become a must-have reference book!' Ivan Nourdin, University of Luxembourg
'The book provides a concise and self-contained exposition of the subject including recent developments.' Maria Gordina, MathSciNet
'The book is written very clearly and precisely, and will be useful to anyone who wants to study the Malliavin calculus and its applications at the introductory level and then more deeply, as well as those who are ready to apply these results in their research. The book can be used to give lectures for graduate students.' Yuliya S. Mishura, zbMath
Descriere
A compact introduction to this active and powerful area of research, combining basic theory, core techniques, and recent applications.