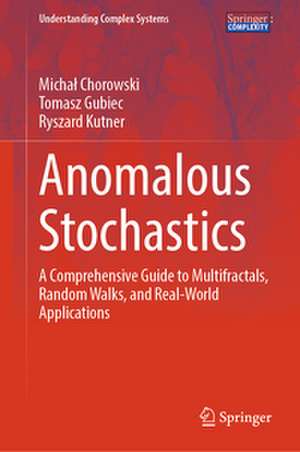
Anomalous Stochastics: Understanding Complex Systems
Autor Micha¿ Chorowski, Tomasz Gubiec, Ryszard Kutneren Limba Engleză Hardback – 2 apr 2025
Din seria Understanding Complex Systems
- 18%
 Preț: 1160.05 lei
-
 Preț: 452.41 lei
- 18%
 Preț: 988.65 lei
- 15%
 Preț: 661.12 lei
- 18%
 Preț: 1170.06 lei
- 18%
 Preț: 911.29 lei
- 15%
 Preț: 667.19 lei
- 15%
 Preț: 673.77 lei
- 15%
 Preț: 675.52 lei
- 18%
 Preț: 955.93 lei
- 18%
 Preț: 990.14 lei
- 15%
 Preț: 666.14 lei
- 15%
 Preț: 663.50 lei
-
 Preț: 442.26 lei
- 15%
 Preț: 661.83 lei
- 15%
 Preț: 677.28 lei
- 15%
 Preț: 666.40 lei
- 20%
 Preț: 674.28 lei
- 20%
 Preț: 677.98 lei
- 18%
 Preț: 982.53 lei
- 18%
 Preț: 1150.57 lei
- 18%
 Preț: 1280.17 lei
- 15%
 Preț: 668.60 lei
- 18%
 Preț: 983.43 lei
- 15%
 Preț: 669.20 lei
- 18%
 Preț: 1440.00 lei
- 18%
 Preț: 990.35 lei
-
 Preț: 414.85 lei
- 18%
 Preț: 980.03 lei
- 18%
 Preț: 1297.31 lei
- 15%
 Preț: 666.97 lei
- 5%
 Preț: 1465.64 lei
- 18%
 Preț: 984.66 lei
- 18%
 Preț: 982.96 lei
-
 Preț: 402.76 lei
- 20%
 Preț: 680.46 lei
- 18%
 Preț: 1047.87 lei
Preț: 500.75 lei
Preț vechi: 589.12 lei
-15%
Puncte Express: 751
Carte tipărită la comandă
Livrare economică 02-16 decembrie
Livrare prin curier în România Termenul estimat este afișat lângă disponibilitate.
Transport gratuit pentru acest produs Plată online sau ramburs, în funcție de opțiunile comenzii.
Retur gratuit în 14 zile Comandă securizată și suport în română.
Specificații
ISBN-13: 9783031803918
ISBN-10: 3031803914
Pagini: 420
Dimensiuni: 160 x 241 x 29 mm
Greutate: 0.74 kg
Editura: Springer
Colecția Understanding Complex Systems
Seria Understanding Complex Systems
ISBN-10: 3031803914
Pagini: 420
Dimensiuni: 160 x 241 x 29 mm
Greutate: 0.74 kg
Editura: Springer
Colecția Understanding Complex Systems
Seria Understanding Complex Systems
Notă biografică
Michä Chorowski is a researcher and quantitative analyst with a robust background in physics, psychology, and computational modeling. Currently, he serves as a Quantitative User Experience (UX) Researcher at Google, where he applies his expertise in data analysis and quantitative methods to measure and evaluate the user experience of digital products and services.
Simultaneously, Michä is pursuing a PhD in Physics at the Faculty of Physics University of Warsaw, under the supervision of Professor Ryszard Kutner. His academic research focuses on modeling critical phenomena in economic markets, time series forecasting, and multifractal analysis. Through his work, he aims to contribute to a deeper understanding of market behavior and forecasting methodologies.
Michä has gained valuable experience in the finance industry while working as a Projections Modeller in the Quantitative Strategies Team at Credit Suisse. In this capacity, he developed mathematical models for scenario-based stress testing and risk assessments, thereby enhancing risk management practices. He holds an MSc in Psychology from the University of Warsaw, where he explored the psychological factors influencing product trends and forecasting in his thesis. Additionally, he earned an MSc in Physics from the Faculty of Physics at the University of Warsaw, specializing in Econophysics, with a focus on modeling government intervention in technology development and innovation diffusion. His exceptional work was recognized when he received the first prize for the best Master's thesis from the Physics in Economics and Social Sciences (FENS) section of the Polish Physical Society in 2021.
Michä Chorowski's research findings have been published in international journals and presented at various academic conferences, contributing to the advancement of knowledge in his fields of expertise.
Tomasz Gubiec earned his MSc in Physics from the University of Warsaw in 2007, followed by a PhD in Physics from the same institution in 2011. He was awarded a Fulbright Scholarship, which enabled him to pursue his studies at Boston University. Additionally, he received the Foundation for Polish Science START Scholarship, further supporting his research endeavors. During his time at Boston University, Tomasz had the privilege of working under the guidance of Professor Eugene Stanley. His research focused on stochastic processes and econophysics, integrating principles from physics and economics to gain insights into complex financial systems.
Tomasz's expertise and interdisciplinary approach led him to assume a leadership role in an interdisciplinary research group, where he extensively analyzed the stability of the Polish interbank market. Currently, he holds the position of Assistant Professor at the Faculty of Physics University of Warsaw. In addition to his academic responsibilities, he also serves as a consultant for hedge funds, leveraging his in-depth understanding of financial markets and stochastic processes to provide valuable insights and guidance.
Tomasz's research findings have been widely recognized and disseminated through his publication of over 20 research articles in reputable scientific journals. His work has made significant contributions to the fields of stochastic processes, econophysics, and agent-based modeling in finance. Committed to advancing scientific knowledge, Tomasz is also passionate about popularizing science among the general public. His efforts in this regard were acknowledged when he received the first prize in the popularization of science competition INTER, organized by the Foundation for Polish Science.
With 15 years of experience in teaching stochastic processes, Tomasz has played a crucial role in shaping the education of aspiring physicists and researchers in this specialized field. His expertise, combined with his passion for teaching, has helped cultivate a new generation of scholars equipped with a solid understanding of s